
You Adopted the Old Money Mindset — Your Life Changed

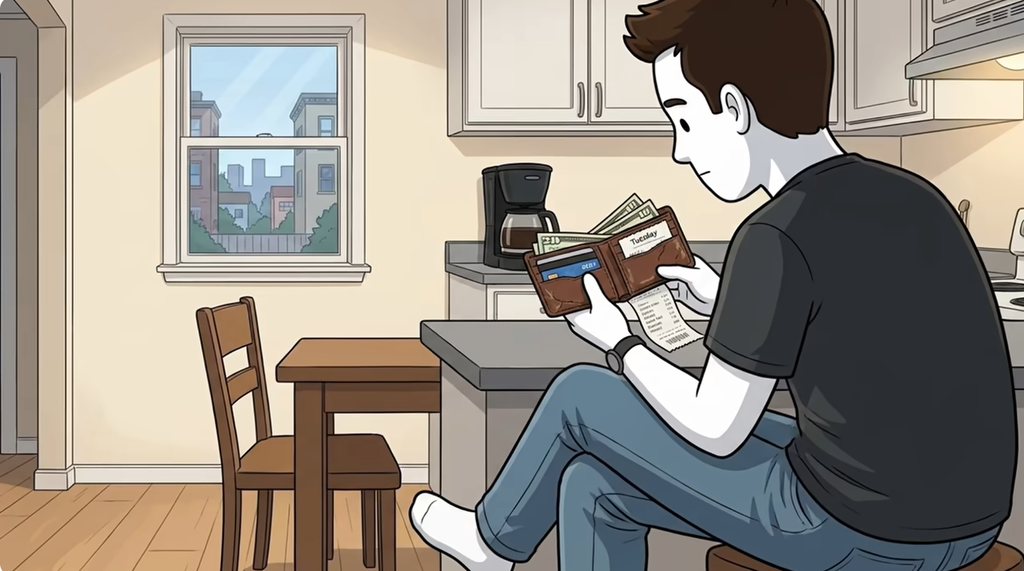
It’s 6:58 on a Wednesday morning, and you’re standing in the kitchen holding your grandfather’s wallet.
It’s brown leather, cracked along the fold, with stitching that has gone gray in one corner. It isn’t worth anything.
You checked once out of curiosity. Maybe $11 if a collector were feeling generous.
Inside it are your debit card, $42 in cash, and a grocery receipt from Tuesday.
Your coworker, Derek, has a carbon-fiber wallet that cost more than your grocery bill this week. His truck is 11 months old. Yours is 19 years old and starts on the second try every time, as if it’s proving something.
Here’s the strange part.
Derek makes about what you make. Maybe a little more.
But your brokerage account crossed $214,000 last month, while Derek has $3,100 in his savings account. Neither of you has ever said a number out loud to the other.
You look poorer than you are.
Derek looks richer than he is.
Nobody in the break room knows either fact.
You didn’t plan for it to work out this way. Nine years ago, you weren’t thinking about net worth.
You were thinking about rent.
But somewhere during those nine years, without a single dramatic moment you could point to, you picked up a way of thinking about money that your grandfather had and never once explained out loud.
You simply watched him live it.
And eventually, you started living it too.
This is the story of how that happened—and what it cost you along the way.
Level 1: The Wallet You Didn’t Ask For
You’re 23.
The apartment costs $850 a month, which felt like a lot until you saw what a one-bedroom closer to downtown cost.
Your paycheck lands every other Friday: $1,486 after taxes.
By the time rent, car insurance, and the credit-card minimum are paid, there’s usually around $180 left to get you to the next paycheck.
Your grandfather dies in March.
At the funeral, your uncle hands you a shoebox.
Inside are a pocketknife, a fishing lure, and the wallet.
Nobody wants the wallet.
It’s ugly. It’s old. It smells like a garage.
You take it anyway.
Three weeks later, you’re going through his desk drawer while helping your mother decide what to keep. That’s when you find a spiral notebook.
The handwriting is so small it’s almost illegible.
There are rows of numbers going back to 1979.
Deposits.
Mostly no withdrawals.
Just deposits, month after month. Sometimes only $25.
Your mother tells you a story you’d never heard.
He made $34,000 a year for most of his working life, driving a delivery route.
He never made six figures. Not once.
He also retired at 61 with more money than two of his brothers who had out-earned him by double.
“He just never stopped,” she says.
That’s the whole thing.
He just never stopped.
You don’t decide to become like him—not consciously.
But that Friday, you open your bank’s app and set up something you’d never set up before.
An automatic transfer.
$50 moves out of checking the day after each paycheck lands and into an index fund you picked because it had the words “total market” in the name. You didn’t know enough yet to overthink it.
$50 isn’t much.
It barely covers a tank of gas.
But it’s automatic now, which means it doesn’t require you to be disciplined every payday.
It simply requires you not to turn it off.
Six months later, the account has $412 in it, and you’ve genuinely forgotten it exists most weeks.
That’s the part nobody tells you about the beginning of wealth building.
It’s not exciting.
It’s not supposed to be.
Level 2: The Years When Nothing Happened
Two years pass.
Then three.
You get a raise.
It’s modest—$2,100 a year.
Instead of feeling it in your lifestyle, you feel it once in a spreadsheet when you increase the automatic transfer from $50 to $110.
Nobody sees this happen.
There’s no announcement.
You don’t tell Derek.
You don’t tell your girlfriend, Priya.
Not because you’re hiding it, but because there is genuinely nothing to say.
The transfer simply changes by $60 a month, and life continues exactly as it did before.
This is the part of building wealth that most people skip when they tell the story.
It’s boring.
And it should be.
Because it was boring to live, too.
Derek buys a truck that year.
$612 a month for six years.
You ride in it once.
There is new-car smell, a dashboard screen the size of a laptop, and you don’t think anything bad about it.
He works hard.
He likes trucks.
It’s his money.
“You should trade that thing in,” he tells you one afternoon, nodding toward your car in the parking lot. “You can afford better.”
“Probably,” you say.
And you mean it.
You can afford better.
You just don’t especially want it.
He’s not wrong.
He’s simply missing the actual math because he’s never seen it.
Your $110 a month, sitting quietly and compounding over time, doesn’t look like anything on a random Tuesday.
It looks like a small number that barely moves.
That’s exactly why it works.
Nobody defends against a threat that looks like nothing.
By the time you’re 27, the account has grown to $9,800.
Partly from your contributions.
Partly from growth on top of growth.
That’s the part your grandfather’s notebook never fully explained, but you’re beginning to understand by watching your own money grow.
Derek’s truck, meanwhile, is worth about $19,000 less than what he’s paid into it so far.
You don’t say any of this to him.
You don’t judge him for it either.
He’s not reckless.
He simply never had a reason to think about money differently.
Neither did you—until a shoebox showed up.
That’s also the year you meet Priya at a mutual friend’s birthday dinner.
She’s a physical therapist and practical about most things.
On your third date, she asks what you do with your money, half-jokingly, testing whether you’re going to say something embarrassing.
“I automate most of it and try not to look,” you tell her.
“That’s the least romantic answer I’ve ever heard,” she says.
But she remembers it.
Months later, she tells you it’s one reason she took a second date seriously in the first place.
Not the answer itself.
The fact that you had one.
There’s a coffee machine in the break room at work that’s been broken for two years, dripping onto a folded paper towel someone replaces every few days.
Derek constantly talks about replacing it.
You’ve started bringing your own thermos instead.
Not to save money exactly.
$9,800 doesn’t hinge on coffee.
It has simply become a small, private ritual.
Fill it Sunday night.
Grab it on the way out.
One less decision every morning.
None of this looks like anything from the outside.
That’s exactly the point.
Level 3: When Your Wealth Starts to Feel Real
You’re 29 when the account crosses $50,000.
It happens on a Sunday morning, quietly, the way everything in this story happens.
You’re drinking coffee from the same mug you’ve had since college.
You check the app out of habit.
And there it is.
$50,140.
You sit with that for a minute.
$50,000 is the kind of number that used to exist only in headlines about other people.
Now it’s sitting in an account with your name on it.
And you earned almost none of it through raw effort during the last 12 months.
Most of the growth came from money that was already there, doing something on its own while you were at work, asleep, on vacation, or arguing with Priya about paint colors.
That’s the first time the math genuinely surprises you.
Your contributions that year: $2,880.
The account’s growth that year: $4,760.
For the first time, the money made more than you put in.
You don’t fully register what that means yet.
You will later.
That’s also the year the test shows up.
Priya’s brother is getting married, and somewhere in the middle of wedding season, you both start talking about upgrading.
A nicer place?
A real dining table instead of the folding one?
Maybe a car that doesn’t have 190,000 miles on it?
It’s not unreasonable.
You can afford some of it now.
You do upgrade the apartment.
$1,450 a month instead of $850.
That one, you decide, actually improves your life.
More space.
A real kitchen.
Somewhere you’re not embarrassed to have people over.
The car doesn’t change.
“Why not?” Priya asks, not annoyed, genuinely curious. “You could get something nice. You’ve earned it.”
You try to explain it, and it comes out clumsy.
“It’s not about the car. It’s about what happens to the $110-turned-$300-a-month transfer if I also take on a $540 car payment.”
You’ve done the math enough times now to understand what that trade-off can cost you years into the future.
It’s not simply a car payment.
It’s money that could have remained invested and continued compounding.
She doesn’t fully get it.
That’s okay.
You’re not sure you would have gotten it either three years ago.
The market drops 19% that autumn, one of those stretches where every headline uses the word “plunge.”
Derek asks you, half-joking and half-serious, whether you’re doing okay with all that stock stuff.
You check the account twice that week.
That’s more than you’ve checked it in the previous six months combined.
The number is smaller.
Genuinely smaller.
Not on paper.
In fact.
You don’t sell anything.
You don’t even seriously consider it.
Instead, you increase the automatic transfer by $40 because you remember something from your grandfather’s notebook.
There was a stretch in the early 80s when the deposits kept coming.
Even though everything around him must have looked uncertain too, the deposits continued.
He never explained why.
He just never stopped.
By spring, the account has recovered—and then some.
You don’t feel triumphant about it.
You mostly feel like you didn’t need to check it twice that week after all.
Level 4: The Financial Crossover
You’re 32 when the transmission goes.
$2,300 to fix it on a car that’s now worth maybe $3,800 total.
The old version of you—the version with $180 left after rent—would have spiraled for a week over a bill like that.
You transfer the money from checking.
You don’t check your credit-card balance to see whether you can absorb it.
You don’t lie awake doing the math.
It’s simply a bill.
Then it’s paid.
Then you’re thinking about what to make for dinner.
The account is $187,000 that spring.
Your monthly contribution is now $650, automated, untouched, and invisible to almost everyone in your life.
And here’s the number that actually changes something in your chest when you calculate it for the first time.
The portfolio’s average growth over the last several years, in dollar terms, is now larger than what you’re putting into it every year from your paycheck.
The money is out-earning you.
Not your job.
The money.
Your job still pays for groceries, the new apartment, and health insurance.
But for the first time, the biggest driver of your future net worth isn’t your effort anymore.
It’s decisions you made years ago.
Those decisions are compounding without needing you to show up every day.
You don’t quit anything.
You don’t tell your boss anything.
Nothing about your outside life changes.
You still park in the same spot.
You still eat lunch at the same desk.
But something has shifted underneath all of it.
Quietly.
The same way the account itself grew.
Without a single dramatic Tuesday to mark the occasion.
Derek gets laid off that November.
Company restructuring.
Nothing personal.
Seventeen people are let go in one afternoon.
He’s not reckless.
He had been saving—just less, just later, just differently, because nobody ever handed him a shoebox.
He finds another job in four months, but those four months are rough.
Credit-card balances climb.
The truck payment doesn’t pause for unemployment.
You help him with $1,200.
No interest.
No spreadsheet.
No lecture.
He pays it back within the year, unprompted, and neither of you brings it up again.
That’s the part your grandfather’s notebook never showed you.
And it’s the part you learn on your own.
The money isn’t just protection for you anymore.
It’s slack.
Room to help without it costing you anything real.
Priya moves in that year.
The wallet comes up exactly once when she’s unpacking a drawer and finds it sitting there, cracked open at the fold.
“You should really get a new wallet,” she says, not unkindly.
The same way she used to say it about the car.
“Probably,” you say.
You don’t replace it.
She doesn’t push.
By now, she’s learned that the things you refuse to upgrade are rarely about the object itself.
Level 5: Having To Versus Choosing To
At 35, your manager offers you a promotion.
More money.
More hours.
More travel.
A title with “senior” in front of it that you would have chased hard at 26.
You take two days to think about it.
Then you turn it down.
Not because you don’t want to grow.
Because you do.
You simply calculate what the extra $14,000 a year is actually worth against 40 more nights a year away from home.
You compare a job you currently like with a job you’re not sure you would.
And you realize, perhaps for the first time in your adult life, that you’re allowed to say no to more money.
Your manager is surprised.
Nobody turns this down.
But nobody at your company knows what’s sitting in that brokerage account either because you’ve never told anyone the number.
Not Derek.
Not your team.
Not even your mother, though she suspects.
The portfolio crosses $410,000 that year.
You don’t buy anything with it.
That’s the part that would confuse someone watching from the outside.
You still drive the same car.
It’s 25 years old now, held together partly by stubbornness.
And Priya has stopped asking about upgrading it because she’s finally seen the version of the spreadsheet you keep—the one that shows what the car’s replacement could cost across decades of lost compounding.
Now she gets it in a way she didn’t at 29.
What the money buys you instead is smaller and harder to photograph.
You take a Tuesday off with no explanation, simply because you can.
You help your sister with a security deposit without needing to check your account first.
You sit in a meeting where your boss pushes a deadline that used to make your stomach drop.
This time, it doesn’t.
You could leave.
You’re choosing not to.
Those are different feelings entirely.
And you didn’t know that until you had both available to you.
Derek gets his fifth truck that year.
A lease this time.
He explains it to you unprompted, almost defensively, like he’s rehearsed the justification before you asked for one.
You didn’t ask.
You never do.
He’s making good money now—better than you in salary terms.
And there’s a version of this story where that fact would bother you.
It doesn’t.
You stopped comparing your trajectory to his somewhere around 29, once you understood that you were playing a different game with a different scoreboard.
He had never been shown the rules.
“You ever think about what you’re gonna do with all that boring index-fund money?” he asks you once.
Only half-joking.
Curious.
A little wary, as if he suspects there’s a number behind it he’d rather not know.
“Not really,” you say.
It isn’t quite true.
But it’s close enough.
And it’s not a conversation either of you actually wants to have standing in a parking garage on a Thursday.
Level 6: The Hidden Cost of Financial Security
Here’s what nobody warns you about getting here.
At 38, you go to a barbecue at Mike’s place.
He’s a guy from your old apartment complex, the one everyone always described as doing really well.
Mike has the house with the pool.
Two cars sit in the driveway, both less than two years old.
There’s a boat he mentions twice in one conversation.
You genuinely like Mike.
He’s generous.
He’s funny.
He’s the kind of guy who grabs the check without making it a thing.
But somewhere around his second boat story, he mentions, almost offhand, that the market pullback last quarter scared him because most of what’s holding the house, boat, and cars together isn’t equity.
It’s financing.
Stacked on financing.
Dependent on his income.
Never missing a beat.
You don’t say anything.
It’s not your business.
And he’s not doing anything unusual.
Most people around you are living some version of Mike’s life.
That’s what makes it strange to be the outlier instead.
Because here’s the truth you didn’t expect.
Being financially fine, quietly, while looking financially unremarkable, is lonelier than you thought it would be.
You can’t really talk about the number with Derek because it would change how he sees every conversation you’ve ever had.
You can’t talk about it at the barbecue because it would make Mike’s boat stories feel smaller than he means them to be.
You’ve gotten used to a strange kind of invisibility.
Wealthy enough that money has mostly stopped being a source of fear.
Quiet enough about it that almost nobody around you has any idea.
Your old friend group used to talk about money constantly.
Who got a raise.
Who’s underwater on their car.
Whose rent went up.
You used to be part of those conversations in a real way, complaining alongside everyone.
Now you mostly listen.
Not because you feel superior.
You don’t.
You got a shoebox.
And 40 years of somebody else’s discipline handed you a starting point most people never get.
You know that.
But you also know the conversations don’t include you the way they used to.
Some part of you misses being fully inside them.
That’s the cost nobody put on the spreadsheet.
Not taxes.
Not fees.
Not market risk.
Just a quiet kind of distance that appears once the outcome starts to separate from the people who were with you at the start.
You wouldn’t trade it back.
But you didn’t expect it either.
Level 7: What Financial Independence Actually Looks Like
You’re 41 now.
It’s a Wednesday morning again.
You’re standing in the same kitchen, although it’s a different apartment from the one you started in.
The same worn wallet is sitting on the counter because you never replaced it.
The stitching finally gave out last year.
You had it repaired for $40 at a shop that mostly fixes boots.
The guy behind the counter asked if you wanted a new one instead.
You said no.
Derek is on his fourth truck now.
Still a good guy.
Still someone you’d call if your car broke down at midnight—which it did once, and he came.
You’ve never told him the number.
You probably never will.
Not because you’re ashamed of it.
Because it was never really about the number to begin with.
The account is $1.1 million this spring.
You checked once, the way you check most things now.
Quietly.
Without much reaction.
The way you’d check the weather.
The version of you sitting in the parking lot at 23, doing math on $180 to get through two weeks, would not believe this number.
That version of you also wouldn’t believe how little it changed day to day once it arrived.
Your grandfather never explained the notebook.
He never sat you down and taught you compound interest, diversification, or dollar-cost averaging.
He just deposited $25 a month for 40 years.
And let the wallet get old instead of the discipline.
You didn’t inherit his money.
There wasn’t much of it in the end, split three ways.
You inherited the only thing that actually mattered.
You watched someone do something unremarkable, consistently, for longer than felt reasonable.
The wallet is still ugly.
It’s still worth about $11 to a collector.
It still holds your card, some cash, and, this week, a receipt from Tuesday.
Everything about your outside life looks almost exactly the way it did nine years ago.
The car.
The wallet.
The parking lot.
What’s changed is entirely underneath the surface.
It’s in a place nobody at the barbecue and nobody in the break room will ever see.
Which, it turns out, was the whole point all along.
What the Old Money Mindset Really Means
The lesson isn’t that you need an old wallet.
It’s not that driving an old car automatically makes someone wealthy.
And it’s not that buying something nice is always a bad financial decision.
The deeper lesson is the mindset behind the choices.
The old money mindset in this story is built around several simple behaviors:
- Spending less than you earn.
- Automating savings and investing.
- Increasing contributions when income increases.
- Allowing investments time to compound.
- Avoiding unnecessary lifestyle inflation.
- Understanding the long-term cost of recurring payments.
- Building financial flexibility before you desperately need it.
- Choosing freedom and flexibility over appearances.
- Measuring wealth by financial security rather than visible consumption.
- Staying consistent when financial progress feels boring.
None of these choices looks dramatic on a random Tuesday.
That’s precisely what makes them powerful.
The goal isn’t necessarily to look wealthy.
It’s to become financially secure.
Looking Rich vs. Being Financially Secure
There is a fundamental difference between looking wealthy and building wealth.
A new truck is visible.
An investment account isn’t.
A large house is visible.
A strong emergency fund isn’t.
Designer clothing is visible.
Decades of consistent investing aren’t.
A boat can demonstrate purchasing power.
Financial independence can exist without anyone noticing it.
The story of the wallet captures that difference.
Derek may have the newer truck.
Mike may have the house, cars, and boat.
But visible consumption doesn’t tell you the complete financial story of a person.
The real measure is what exists underneath the surface.
How much do you own?
How much do you owe?
How much of your income is already committed?
How much flexibility would you have if your income suddenly disappeared?
And how much of your future has already been funded by decisions you made years ago?
The Power of Consistent Wealth Building
The grandfather’s behavior is simple.
$25 a month.
Then another month.
Then another.
Then another.
There is nothing spectacular about one deposit.
The transformation comes from repetition.
That is one of the central ideas behind long-term wealth building.
A small amount of money invested consistently can become meaningful when contributions continue for decades and investment returns compound over time.
The important distinction is that the story isn’t presenting wealth as a result of one lucky investment.
It is presenting wealth as the result of behavior repeated for a long time.
The discipline comes first.
The visible result comes later.
Why Financial Security Changes Your Choices
By the time the account reaches $187,000, the money does more than sit on a screen.
It changes what a $2,300 repair means.
It changes what unemployment means.
It changes whether helping someone requires putting your own finances at risk.
Eventually, it changes how you think about work.
At 35, the extra $14,000 from a promotion isn’t automatically worth accepting.
Why?
Because money is no longer the only variable.
Time matters.
Family matters.
Freedom matters.
The ability to say no matters.
Financial security gives you choices that weren’t available when every paycheck was already spoken for.
That’s a different kind of wealth.
The Real Meaning of the Wallet
The wallet was never valuable because it was made of leather.
It wasn’t valuable because it was old.
It wasn’t valuable because a collector might pay $11 for it.
It became valuable because it represented a behavior.
Your grandfather didn’t leave you a fortune.
He left you evidence.
A notebook filled with decades of deposits.
A wallet that survived longer than most people’s financial plans.
And a lesson that was never delivered as a lecture.
He just never stopped.
That’s the old money mindset at its simplest.
Not looking rich.
Not chasing every upgrade.
Not trying to prove anything.
Just building something quietly and giving it enough time to become difficult to ignore.
Final Thought: Wealth Doesn’t Always Look Like Wealth
The person with the newest car may have the largest payment.
The person with the oldest car may have the largest investment account.
The person wearing the expensive watch may be financing it.
The person wearing an old watch may own the business across town.
You cannot determine someone’s financial position simply by looking at them.
And you don’t need other people to see your progress for your progress to matter.
At 23, you had $180 left after paying your bills.
At 41, you have $1.1 million.
The biggest change wasn’t the wallet.
It wasn’t the car.
It wasn’t the apartment.
It wasn’t even the investment account.
The biggest change was the way you thought about money.
You stopped asking, “What can I afford today?”
And slowly started asking, “What will this decision cost me tomorrow?”
You stopped trying to look financially successful.
You started building financial security instead.
And after enough years of doing that quietly, the difference became impossible to ignore.
If this story made you think differently about what looking rich versus being financially secure actually means, share it with someone who might need to hear it.
And ask yourself:
Is there an object in your own life—like this wallet—that is quietly connected to the way you think about money?


